Blog

  • Using a Virtual Card With Apple Pay and Google Pay

    Using a Virtual Card With Apple Pay and Google Pay

    Example scenario: you buy a virtual card for online subscriptions and notice it could also pay at the coffee shop if it were in your phone wallet. You open Apple Wallet, type in the number, and get “Card Not Supported”. Your friend adds a different virtual card to Google Wallet in under a minute. Same phone type, same kind of card, different result.

    Using a virtual card with Apple Pay or Google Pay is common, and when it works it turns an online-only card into one you can tap in stores. Whether it works depends on decisions made by the card issuer and the wallet, not on you. This guide explains how wallet provisioning works, walks through the steps for both wallets, and covers the reasons a card gets refused.

    How adding a card to a wallet works

    When you add a card to Apple Pay or Google Pay, the wallet does not simply store your card number. It asks the card network and the issuer to create a separate device token, a stand-in number tied to your phone or watch. When you tap or pay in an app, the merchant receives that token instead of your real card number.

    That process involves three parties, and any one of them can say no:

    • The wallet must be available in your country or region, on your device.
    • The card network (Visa, Mastercard and so on) must support tokenization for that card.
    • The issuer (the bank or institution behind the card) must take part in that wallet and approve this specific card. Issuers often verify you with a code by text, email or app before activating the token.

    Apple’s own support pages note that some cards from participating banks may not be supported, which tells you approval happens card by card, not bank by bank.

    Where it works and where it doesn’t

    FactorUsually works whenOften fails when
    Wallet countryThe wallet supports payments in your country or regionThe wallet is not available where you live
    Issuer participationThe issuer takes part in that walletThe issuer has not enabled the wallet, or not for this card type
    Card typeThe issuer allows the card type (some allow prepaid, some do not)The issuer excludes prepaid or virtual cards from wallets
    VerificationYou can receive the issuer’s code or confirm in its appThe issuer cannot reach you or the details do not match
    MerchantThe store takes contactless or the site offers Apple Pay or Google PayThe merchant does not offer the wallet at checkout

    Apple publishes Apple’s list of countries and regions that support Apple Pay, and Google has Google’s supported countries page for Google Wallet, with features such as tap to pay listed by country. Check both before you assume a card will work.

    How to add a virtual card to Apple Pay

    1. Open the Wallet app on your iPhone and tap the plus button.
    2. Choose to add a debit or credit card. Prepaid cards are added through the same option.
    3. Enter the card details manually: card number, expiry date, security code and the cardholder name. Use the details exactly as shown by the provider.
    4. Accept the issuer’s terms if asked. These come from the card issuer, not Apple.
    5. Complete verification by entering the code the issuer sends, or follow its instructions.
    6. Test it with a small contactless purchase or an online checkout that offers Apple Pay.

    To use the card on an Apple Watch, add it again through the Watch app. Each device gets its own token.

    How to add a virtual card to Google Pay

    1. Open Google Wallet on your Android phone and tap “Add to Wallet”.
    2. Choose payment card, then new credit or debit card.
    3. Enter the card details manually: number, expiry, security code and billing address.
    4. Accept the issuer’s terms and complete verification.
    5. Set up a screen lock if prompted. Google Wallet requires one for tap to pay.
    6. Test it with a small payment in a store or app.

    Menu labels change between app versions, so look for the closest match if yours differs.

    Troubleshooting common errors

    “Card not supported” or “This card can’t be added”

    The issuer has not enabled this card for the wallet, or not in your country. Nothing on your side fixes this. Ask the provider whether the card supports that wallet.

    “Contact your card issuer”

    Provisioning started but the issuer did not approve it automatically. The issuer may need to verify you. Contact the provider’s support with the error message.

    Verification code never arrives

    Check that the contact details the provider holds are current, then try again later. Repeated attempts in a short time can trigger extra checks.

    Card added but payment declined

    Check the balance, the card’s freeze status and whether the merchant accepts that network. A prepaid card with too little balance is declined like any other card.

    Should I change my phone’s region to make it work?

    No. Changing device region to force a wallet can break other services and may go against the wallet’s terms. If the wallet or issuer does not support your country, use the card online instead.

    Is a wallet safer than typing the card number?

    In most cases, yes. The merchant receives a device token rather than your card number, and each payment is confirmed with Face ID, Touch ID, fingerprint or passcode. If your phone is lost, you can remove cards remotely. The underlying card still matters: if the card itself is compromised online, freeze it with the provider.

    Example: Vizovcc cards in a phone wallet

    Vizovcc sells prepaid virtual cards and its card pages show Apple Pay and Google Pay compatibility. That makes it a useful example of how this works in practice, and of the limits.

    You fund a Vizovcc balance with crypto, buy a card, and the number, expiry and security code appear in the dashboard once the card is ready, often within minutes. From there, you add the card to Apple Wallet or Google Wallet using the manual steps above. You can read more about its prepaid Visa and Mastercard cards on the Vizovcc site.

    The honest caveat applies here as it does to every provider: whether any card can be added to a wallet depends on the card issuer and on the wallet’s rules in your country. A card page showing wallet compatibility tells you the card type has supported wallets, not that every phone in every country will accept it. Before you buy:

    • Check the specific card page for its wallet notes and currency.
    • Confirm Apple Pay or Google Pay works in your country using the official lists.
    • Remember that card purchases are final, so make sure the card fits your use before buying.
    • Keep enough balance for the purchase, since the card is prepaid and cannot go below zero.

    Other Vizovcc features carry over to wallet use: you can freeze and unfreeze a card from the dashboard, cards support 3D Secure for online checkouts, and you can hold several cards from one balance. Funding is crypto only, and any merchant can still decline a prepaid card.

    FAQ

    Can prepaid virtual cards be added to Apple Pay?

    Many can, if the issuer allows prepaid cards in Apple Pay and Apple Pay is available in your country. Some issuers exclude prepaid cards.

    Does Google Pay work with virtual cards?

    Yes, when the issuer supports Google Wallet for that card and tap to pay is available in your country. Online payments in apps and websites have their own country list.

    Do I need the physical card to add a card to a wallet?

    No. You enter the number manually, which is how virtual cards are added.

    Key takeaways

    • Wallets create a device token for your card, and the issuer must approve each card.
    • Wallet country, issuer participation and card type decide whether a card can be added.
    • “Card not supported” is an issuer or country decision, not something you can fix on your phone.
    • Check the official country lists and the card page before buying a card for wallet use.
    • Wallet payments hide your card number from merchants, which is a security plus.

    Before you buy any virtual card for tap-to-pay, check the wallet’s country list and the card’s own page. If you want a prepaid card whose pages list Apple Pay and Google Pay compatibility, take a look at Vizovcc and confirm the details for your country first.

  • Crypto Virtual Cards: How They Work and What They Cost

    Crypto Virtual Cards: How They Work and What They Cost

    Here is a situation many freelancers paid in stablecoins know well. A developer receives her monthly fee in USDT. Her design tools, hosting and AI subscriptions all want a card. Moving the USDT to an exchange, selling it, withdrawing to her bank and waiting for the transfer takes days and costs fees at every step. By the time the money reaches her card, a renewal has already failed.

    A crypto virtual card shortens that path: you send crypto, it becomes spendable card balance, and you pay online with a normal card number. The idea is simple, but the costs and risks sit in places most people don’t look. This guide explains how the top-up flow works, every fee you can meet along the way, the tax and compliance points, and who these cards suit.

    Two models behind “crypto cards”

    Products sold as crypto cards usually follow one of two designs:

    • Convert at payment. You keep crypto in an account, and each card payment sells just enough at the moment you pay. Your balance stays in crypto until you spend.
    • Convert at top-up. You send crypto to the provider, it is credited as a balance in a fiat currency such as US dollars, and the card spends that balance. Your exposure to crypto prices ends when the deposit is credited.

    Convert-at-payment suits people who want to stay invested until the last second. Convert-at-top-up suits people who want a predictable dollar amount for bills. Most prepaid virtual card platforms use the second model.

    How a top-up works, step by step

    1. Choose a coin and network. USDT, for example, exists on several blockchains. The provider accepts only specific ones.
    2. Get the deposit details. The provider shows an address and an exact amount, often with a time limit on the quoted price.
    3. Send from your wallet or exchange. You pay the network fee. If an exchange deducts its withdrawal fee from the amount, less arrives than you entered.
    4. Wait for confirmation. The transfer is confirmed on the blockchain, then checked by the provider.
    5. Balance credited. The deposit becomes spendable balance, often in US dollars.
    6. Buy or fund a card. You use the balance for a virtual card and enter its details at the merchant.

    The mistake that can’t be undone

    Sending on the wrong network is the most expensive error. If a provider accepts USDT on TRON (TRC-20) and you send it on Ethereum or BNB Smart Chain, the funds may never be credited, because blockchain transfers can’t be reversed. Always match both the coin and the network shown on the deposit page, and send a small test amount first if the provider allows it.

    Every cost you might pay

    A crypto virtual card can be cheap or expensive depending on how many of these layers apply:

    Cost layerWho charges itHow to keep it low
    Buying the cryptoExchange or on-ramp spread and trading feeSkip this layer if you already earn or hold crypto
    Withdrawal feeYour exchange, when sending outCompare networks; fees vary widely by chain
    Network feeThe blockchain (paid to validators or burned)Low-fee networks such as TRON or Solana usually cost less than Bitcoin
    Conversion spread or top-up feeThe card providerCheck that the provider shows its rate or fee before you send
    Card feesThe card provider: issue, monthly and per-payment feesPrefer one-time fees over monthly fees if you hold several cards
    Foreign exchangeCard issuer, if the card’s currency differs from the merchant’sUse a card in the currency the merchant bills in
    Price movementThe market, for volatile coins between sending and creditingUse stablecoins, and send before a quoted price expires

    Stablecoins versus volatile coins

    USDT is designed to stay close to one US dollar, which makes it the natural choice for paying bills. Bitcoin and SOL can move in the minutes or hours between sending and crediting, and Bitcoin usually takes longer to confirm. If the amount matters, fund with a stablecoin and keep volatile coins for holding.

    Tax and compliance: what doesn’t change

    Spending crypto is usually a taxable event, even when it feels like moving money between your own pockets. In the US, the IRS’s FAQ on digital asset transactions states that digital assets are treated as property, and that paying for services with them is a disposal that can produce a capital gain or loss. Converting crypto into card balance can count the same way. Other countries have their own rules, so keep a record of each deposit’s date, amount and value, and check with a tax adviser where you live.

    Crypto funding also doesn’t make a card anonymous. Reputable providers may ask for identity verification, screen against sanctions lists and refuse cards from sanctioned countries. A crypto-funded card is a payment tool, not a way around KYC, tax, platform rules or currency controls.

    Who crypto virtual cards suit, and who they don’t

    Good fitPoor fit
    Freelancers and remote workers paid in stablecoinsPeople who would buy crypto only to fund the card, paying spreads twice
    Online businesses that hold crypto revenue and pay for software or adsAnyone who needs credit, rewards or strong chargeback rights
    People whose local cards fail on foreign merchantsPeople who want to avoid identity checks or tax reporting
    Teams that want separate prepaid cards per vendor from one balanceUsers who need in-person payments with a physical card

    A checklist before you choose a provider

    1. Which coins and networks are accepted, and what happens if you use the wrong one?
    2. Is the conversion rate or top-up fee shown before you send?
    3. How long does a quoted price hold?
    4. Which card networks and currencies are available?
    5. What are the issue, monthly and per-payment fees?
    6. Can you withdraw unused balance, in what form, and at what cost?
    7. What happens to your money if a card can’t be issued?
    8. Which identity checks apply, and when?

    Worked example: a USDT-funded card on ZenVCC

    ZenVCC follows the convert-at-top-up model. It is a prepaid virtual card platform, not a bank, and it answers most of the checklist above on its own pages. ZenVCC’s guide to USDT-funded cards walks through the deposit flow in detail.

    • Coins and networks: Bitcoin, TRX, SOL and USDT on TRC-20 or Solana. USDT on other networks, such as ERC-20 or BEP-20, is not accepted, and a wrong-network transfer can’t be credited or recovered.
    • Deposit flow: the deposit page shows an exact amount and address. You send the full amount in one payment before the quoted price expires, then submit the transaction hash. Each deposit is checked on its blockchain before your balance is credited in US dollars.
    • Fees: you pay your wallet’s network fee, and any payment-method charge is shown before you pay. Each card costs its price plus a one-time $10 issue fee, each card payment costs $0.10, and there is no monthly fee.
    • Cards: about 50 cards across Visa, Mastercard, American Express, Maestro and some UnionPay and JCB options, including USD and local-currency cards. Cards are valid for three years.
    • Refunds and withdrawals: if a card can’t be prepared, the full amount, issue fee included, returns to your balance. Unused balance can be withdrawn in crypto, with a $10 minimum and no withdrawal fee, after a review. Money on a card can’t be moved back to the balance.
    • Identity: ZenVCC may ask you to verify your identity before you buy a card, whichever coin you use.

    There are limits to plan around. Cards can’t be topped up from the dashboard, there are no in-app spend limits or card freezing, and a payment that asks for a 3-D Secure code can’t be completed, because the dashboard doesn’t show those codes. Each platform also decides which cards it accepts, so test a new card with a small payment first.

    Key takeaways

    • Most crypto virtual cards convert your crypto at top-up into a dollar balance, then spend it like any prepaid card.
    • Costs stack in layers: exchange, network, provider and card fees, plus exchange rates and price movement.
    • Match the coin and network exactly. Wrong-network transfers usually can’t be recovered.
    • Stablecoins keep the amount predictable for bills.
    • Spending crypto can be taxable, and identity checks still apply.

    Before your next top-up, run through the checklist and add up every cost layer that applies to you. If a prepaid card funded with USDT, Bitcoin, TRX or SOL fits the way you earn and spend, take a look at ZenVCC and compare its fees with your current route from crypto to card.

  • Premium Wedding Transfers for Memorable Celebrations

    Premium Wedding Transfers for Memorable Celebrations

    Elegant Charters, a Perth-based transportation provider, has introduced premium wedding transfer services, expanding its transport options for couples, wedding parties, families and guests preparing for celebrations across Perth and surrounding areas.

    The new service responds to the transportation needs associated with wedding events, where coordinating arrivals, departures and group travel can be an important part of event planning. Through its range of chauffeur-driven vehicles and group transport options, Elegant Charters aims to provide practical travel arrangements for different wedding requirements.

    Addressing Wedding Transportation Needs

    Wedding celebrations often involve multiple venues, guests travelling from different locations and carefully planned event schedules. Organising transportation for couples, bridal parties and family members can present logistical challenges, particularly when several journeys are required throughout the day.

    Reliable transport arrangements can help simplify these movements while allowing wedding organisers and guests to focus on the occasion.

    Additional details are available at: https://share.google/FSAdcLsUiOwdP7pXf

    Elegant Charters’ introduction of wedding transfers adds another option for customers seeking coordinated chauffeur and group transportation in the Perth metropolitan area.

    Company Expands Its Chauffeur and Group Transport Services

    Elegant Charters provides a range of passenger transportation options, including sedans, SUVs, 4–7-seater vehicles and 13–24-seater minibuses and maxi cabs.

    These vehicle categories provide flexibility for different travel requirements, from individual and small-group journeys to transportation involving larger wedding parties and guest groups.

    The company’s wedding transfer offering complements its existing services, which include airport transfers, corporate transportation, event travel, hotel transfers, family trips and long-distance journeys.

    Customers can also access personalised travel arrangements and door-to-door transportation, depending on their requirements.

    Wedding Transfer Options Across Perth

    The wedding transfer service is designed to accommodate different transportation needs associated with wedding celebrations.

    Potential arrangements include:

    • Couple transportation: Private chauffeur-driven travel for couples attending wedding ceremonies and receptions.
    • Bridal party transfers: Vehicle options for transporting members of the wedding party between locations.
    • Guest transportation: Group travel arrangements using minibuses and maxi cabs.
    • Family transfers: Transportation for relatives and family members attending wedding celebrations.
    • Venue-to-venue travel: Transport coordination for journeys between ceremony, photography and reception locations.

    Vehicle selection and travel arrangements can be discussed with the company when requesting a quotation.

    Elegant Charters also offers 24-hour availability, online booking, flexible payment options and free cancellation, subject to applicable booking terms.

    Supporting Transportation Across Perth

    Based in Southern River, Western Australia, Elegant Charters serves customers requiring transportation across Perth and its surrounding areas.

    Beyond wedding-related journeys, the company provides airport transfers, including Perth Airport transportation, corporate travel, tours, cruise transfers, FIFO transportation and event travel.

    Its fleet includes vehicles suited to different passenger capacities, with baby-seat options available for family transportation.

    Customers can request quotes and arrange bookings through the company’s website, providing access to its transportation services throughout the day and night.

    Company Statement

    “Wedding transportation involves more than getting from one destination to another. It requires careful consideration of passenger numbers, schedules and individual travel requirements. Our aim is to give couples, families and wedding organisers access to flexible vehicle options and professional chauffeur services to help make their transportation arrangements easier.”

    Proposed executive quote for company review and approval before publication.

    Looking Ahead

    The introduction of wedding transfers reflects Elegant Charters’ continued expansion of its passenger transportation options in Perth.

    As demand for flexible travel arrangements continues across weddings, private events and group occasions, the company intends to support customers with a range of vehicle choices and booking arrangements.

    Through its combination of chauffeur services, passenger vehicles and larger group transport options, Elegant Charters aims to remain a practical transportation option for individuals, families and organisations planning journeys throughout the Perth region.

    About Elegant Charters

    Elegant Charters is a transportation and chauffeur service provider based in Southern River, Western Australia. The company offers professional chauffeur services and passenger transportation across Perth, including airport transfers, wedding transfers, corporate travel, tours, events, cruise transportation and long-distance journeys.

    Its fleet includes sedans, SUVs, 4–7-seater vehicles and 13–24-seater minibuses and maxi cabs. Additional services include FIFO transfers, family transportation with baby-seat options, personalised travel arrangements and door-to-door journeys.

    Elegant Charters offers 24-hour availability, online booking, quotation requests and flexible payment arrangements.

    Media Contact

    Elegant Charters
    Southern River, WA, Australia
    Phone: +61 458 655 640
    Website: https://elegantcharters.com.au/

  • Valentine Services – Stump Grinding Highlights Tree Stump Removal Benefits for Cincinnati Homeowners

    Valentine Services – Stump Grinding Highlights Tree Stump Removal Benefits for Cincinnati Homeowners

    Valentine Services – Stump Grinding is highlighting the benefits of professional tree stump removal for homeowners and property owners throughout Cincinnati, Ohio, and Northern Kentucky. The company’s stump grinding services address common property concerns associated with leftover tree stumps, including potential tripping hazards, limited yard space, and obstacles to routine landscaping and property maintenance.

    Tree stumps left behind after tree removal can create ongoing challenges for residential and commercial properties. While some property owners choose to leave stumps in place, others seek professional removal to improve outdoor accessibility, prepare areas for landscaping, and reduce potential safety concerns.

    Addressing Common Property Challenges

    Tree stumps can interfere with everyday outdoor activities and affect how property owners use their yards. Exposed roots and remaining stump sections may create uneven surfaces, complicate lawn maintenance, and limit available space for outdoor improvements.

    In Cincinnati and surrounding communities, property owners may encounter these issues following tree removal, storm damage, landscaping projects, or routine property maintenance.

    Professional tree stump removal offers a practical approach to addressing these concerns. Grinding unwanted stumps below the surrounding ground level can help prepare affected areas for future landscaping while reducing obstructions in lawns and outdoor spaces.

    Professional Stump Grinding Services

    Valentine Services – Stump Grinding provides residential and commercial stump grinding solutions for property owners, contractors, businesses, and property managers.

    The company’s services include residential stump grinding, commercial stump grinding, surface root grinding, large stump removal, wood chip cleanup, and site restoration.

    Each project is assessed according to the stump’s size, location, surrounding conditions, and property requirements. The objective is to remove unwanted stump material while helping property owners prepare the affected area for its intended use.

    The company serves Cincinnati and nearby communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland, and Hamilton in Ohio, as well as Florence, Covington, Erlanger, Burlington, and Hebron in Northern Kentucky.

    Benefits of Professional Tree Stump Removal

    Removing unwanted tree stumps can provide several practical benefits for property owners.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    Improved yard safety: Old stumps and exposed surface roots can create obstacles in frequently used outdoor areas. Removing them can help reduce potential tripping hazards.

    More usable outdoor space: Stumps can restrict lawn activities, landscaping plans, and outdoor improvements. Grinding them can make affected areas more accessible.

    Simplified lawn maintenance: Remaining stumps may interfere with mowing and routine yard care. Their removal can make ongoing property maintenance easier.

    Greater landscaping flexibility: Property owners can use cleared areas for grass, garden beds, or other landscaping projects, depending on soil conditions and site preparation requirements.

    Reduced unwanted obstructions: Removing old stump material can help create a more organized and functional outdoor environment.

    Company Background and Service Commitment

    Valentine Services – Stump Grinding serves residential and commercial customers throughout Greater Cincinnati and Northern Kentucky. The company focuses on professional stump grinding and removal, including projects involving unwanted tree stumps, surface roots, and larger stump sections.

    Its service approach emphasizes reliable scheduling, customer communication, and attention to individual property requirements. Valentine Services – Stump Grinding is licensed and insured and provides free estimates for customers considering stump removal work.

    Looking Ahead

    As property owners continue to maintain and improve their outdoor spaces, professional stump grinding remains an important consideration following tree removal and landscaping projects.

    Valentine Services – Stump Grinding will continue serving homeowners, businesses, contractors, and property managers across Cincinnati and Northern Kentucky with stump grinding and removal solutions tailored to individual property needs.

    Property owners interested in removing unwanted tree stumps can contact the company to request a free estimate.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides professional tree stump grinding and removal services throughout Cincinnati, Ohio, and Northern Kentucky. The company works with homeowners, businesses, property managers, and contractors to remove unwanted tree stumps, surface roots, and other obstructions. Its services include residential and commercial stump grinding, large stump removal, root grinding, chip cleanup, and site restoration. Valentine Services – Stump Grinding is licensed and insured and provides free estimates.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: https://www.513stumps.com/

  • TikTok Ads Billing Explained for New Advertisers: Manual vs Automatic Payment

    TikTok Ads Billing Explained for New Advertisers: Manual vs Automatic Payment

    Your first TikTok campaign was approved, spent for a few hours, and then stopped. Ads Manager shows a payment warning or a zero balance, and you can’t tell whether you picked the wrong billing mode, the wrong card, or both.

    Quick answer

    1. Manual payment: you add funds first, and ads spend down that balance. When it reaches zero, delivery stops.

    2. Automatic payment: TikTok charges your card when spend reaches your billing threshold or your bill date, whichever comes first.

    3. The switch is one-way. You can move from manual to automatic, but not back.

    4. Most stalled campaigns come from a balance that ran dry (manual) or a threshold charge the card could not cover (automatic).

    The three billing modes in plain terms

    TikTok’s help center describes three billing options (TikTok billing options).

    Manual payment. You add money to the ad account or Business Center before ads run. TikTok calls this a cash balance. Ads deliver against it, and TikTok will not deliver beyond it. If the balance is too low, campaigns can be paused or rejected. Money left over after a campaign carries forward to the next one.

    Automatic payment. You keep a primary payment method on file. TikTok adds up your ad costs and charges that method when the account reaches its billing threshold or its bill date, whichever comes first. Bill dates can be weekly or monthly, and TikTok sets them from the account’s registration date and spending history. A busy account can be charged several times in one cycle, because every time accrued spend reaches the threshold, a new charge fires.

    Monthly invoicing. This is only for eligible businesses. TikTok sets the spending limit and threshold at its discretion, sends an invoice, and payment is due 30 days from the invoice date unless otherwise agreed. Most new advertisers will not see this option.

    ModeWhen money movesWhat stops your adsSuitsCan switch to
    Manual paymentBefore ads run (you add funds)Balance reaches zeroNew advertisers, fixed budgets, prepaid fundingAutomatic or monthly invoicing
    Automatic paymentAfter spend, at threshold or bill dateA failed chargeSteady spend on an established cardMonthly invoicing only
    Monthly invoicingAfter the month, by invoiceAn unpaid invoice past its termsEstablished businesses TikTok approvesNothing else

    The one-way door: why your first choice matters

    TikTok’s automatic payment article is explicit: once automatic payment is set, you cannot go back to manual payment. The allowed moves are manual to automatic, manual to monthly invoicing, and automatic to monthly invoicing. Nothing moves back toward manual.

    That makes manual payment the safer default for a new account. You can test creative, learn your real cost per day, and move to automatic later once you know what a typical charge looks like. If you start on automatic and your card turns out to be a poor fit, the fix is a new payment method, not a different mode.

    Two other settings are worth getting right at the start, because they are hard to change later:

    • Account currency. If your card settles in USD and your ad account bills in another currency, every charge carries a currency conversion. That can add cost, and it makes reconciliation harder. [VERIFY: whether TikTok lets advertisers change ad account currency after creation.]
    • Business details and country. The country and business information on the ad account decide which payment methods you are offered and which advertising policies apply. A different card does not change those rules.

    How automatic payment actually charges your card

    Under automatic payment, each charge is a card-not-present authorization that TikTok’s processor sends to your card issuer. Nobody is at the keyboard when it happens. The issuer checks the card’s status, the available balance, the merchant category, any spending limits, and its own fraud rules. Then it approves or declines.

    New accounts usually start with a low threshold that can rise as payments succeed [VERIFY: TikTok’s threshold starting level and increase rules; they are not stated on the automatic payment page]. The arithmetic is simple. Suppose, as an illustration, your threshold is $200 and the campaign spends $150 a day. You would see a charge roughly every 32 hours, plus one on the bill date for whatever has accrued since the last charge.

    When a charge fails, the decline reason usually maps to one of a few ISO 8583 response codes:

    • 51, insufficient funds. The card balance did not cover the threshold amount. This is the most common cause on prepaid cards.
    • 05, do not honor. A generic issuer refusal, often a risk rule or a merchant-category block.
    • 54, expired card. The card on file has passed its expiry date.

    TikTok says you may need to make a manual payment when your payment method fails. Repeated failures can pause running campaigns or block new ones until the outstanding amount is paid [VERIFY: the number of failed attempts before TikTok pauses campaigns].

    How manual payment keeps a campaign alive

    With manual payment, the balance is your budget fence. The sizing rule is:

    Balance needed = daily budget × days until your next planned top-up + a buffer.

    A campaign spending $80 a day that you top up every Monday needs at least $560 on the balance, plus a margin for days when delivery runs hot. Funds you add by card may take time to appear on the balance, so top up before the balance gets low, not after delivery stops [VERIFY: how long card top-ups take to post to a TikTok balance].

    Manual payment also suits prepaid cards for a structural reason. The card is only used when you choose to add funds, so you are present for the transaction. If the issuer asks for a 3D Secure challenge, you can complete it. An unattended threshold charge cannot answer a challenge.

    Whether TikTok accepts a prepaid card at all depends on the market and the payment methods offered to your account. TikTok’s billing page says the options “may accept bank transfers, credit card, or other payment methods” but does not mention prepaid cards [VERIFY: TikTok’s accepted card types by region, including prepaid].

    Where a crypto-funded prepaid card fits, and where it doesn’t

    Some advertisers hold their working capital in stablecoins and want a card they can fund from a wallet. VCCBuy’s TikTok Ads card page is one worked example. You fund a USD balance with USDT (TRC20, BEP20, ERC20, Polygon or Solana), USDC or several other coins. Deposits are checked before they are credited. You then issue a prepaid Mastercard or Visa. The Mastercard Prepaid has a 2.5% top-up fee and a $10,000 monthly limit. 3D Secure codes are shown in the dashboard for 10 minutes, without a phone number. You can save a billing name and address per card and freeze a card between campaigns.

    Be clear about the limits. Some merchants and some billing settings decline prepaid cards. VCCBuy is not a bank, it does not take BTC deposits (you swap to a stablecoin first), and TikTok makes its own checks regardless of the card. Other legitimate options include a bank-issued virtual card, a business credit card, or bank transfer where TikTok offers it.

    The account rules do not change with the card. TikTok’s country, business-verification and advertising policies apply to every advertiser. If an account is restricted, the route is TikTok’s appeal process, not a new card or a new account.

    Pre-launch billing checklist

    ☐  Billing mode chosen on purpose. Start on manual unless you already know your spend pattern.

    ☐  Ad account currency matches the currency your card settles in.

    ☐  Business name, country and address in Ads Manager are accurate and match the billing details saved on the card.

    ☐  The card is enabled for online, card-not-present and international transactions.

    ☐  You know how to complete a 3D Secure challenge on this card.

    ☐  Manual: the balance covers every day until your next top-up, plus a buffer of at least one extra day.

    ☐  Automatic: the card balance always covers one full threshold charge plus a day of spend.

    ☐  Payment notification emails go to an inbox someone reads daily.

    ☐  A recurring calendar reminder for top-ups or card balance checks.

    When a campaign stalls: a five-step procedure

    1.  Read the exact message in Ads Manager’s payment section. “Insufficient balance” and “payment failed” are different problems.

    2.  Manual payment: add funds and confirm they posted to the balance. Then check whether paused campaigns resumed or need to be switched back on [VERIFY: whether TikTok resumes paused campaigns automatically after a top-up].

    3.  Automatic payment: open the card’s transaction log. A declined authorization with a reason (insufficient funds, expired) tells you the fix. Top up or replace the card, then settle the outstanding amount from the payment section.

    4.  No attempt on the card at all? Then the block is on TikTok’s side, such as payment-method verification or an account review. Contact TikTok support. Changing cards will not help.

    5.  Do not open a second ad account to get around a payment hold. That breaks TikTok’s terms and usually makes the original problem harder to resolve.

    FAQ

    Can I switch from automatic payment back to manual payment? No. According to TikTok’s help center, automatic payment cannot be changed back to manual. You can only move on to monthly invoicing if you become eligible.

    Why was I charged several times in one week? Under automatic payment, TikTok charges each time accrued spend reaches your billing threshold, and again on the bill date. A daily budget above your threshold produces more than one charge per day.

    Does TikTok accept prepaid cards? It depends on your market and the payment methods your account is offered. TikTok’s billing page does not address prepaid cards directly. If a prepaid card is declined at setup, try manual payment first, where you are present for each transaction.

    Conclusion

    TikTok billing is simple once you see where money moves. Manual payment spends a balance you control, and automatic payment charges whatever card is on file at each threshold. Start manual, size the balance to your real daily spend, and move to automatic only when you know your charges. If you fund ads from stablecoins, a VCCBuy prepaid card with a lean, planned balance is one option worth comparing with your bank’s virtual cards.

    About the author: [Author name] is a payments and fintech writer at VCCBuy (https://vccbuy.net/), where they cover virtual cards, card networks and spending stablecoins online. They write about how ad platforms bill cards and how advertisers can keep campaigns running within each platform’s rules.

    Disclosure: the author writes for VCCBuy, which is mentioned in this article.

  • Asher Movers Introduces Local Moving Services Designed for Stress-Free Moves in Skokie, Illinois

    Asher Movers Introduces Local Moving Services Designed for Stress-Free Moves in Skokie, Illinois

     Asher Movers Local & Long Distance has announced expanded local moving services for homeowners, renters, students, businesses and other customers in Skokie and surrounding Chicago-area communities. The service expansion adds to the company’s existing range of residential and commercial relocation solutions.

    Local moves can involve a range of logistical challenges, from coordinating moving schedules and packing belongings to safely transporting furniture and specialty items. Asher Movers is responding to these needs with moving services structured around the requirements of individual customers and the details of each relocation.

    Addressing Local Moving Challenges

    Moving within the Chicago area may require careful planning around apartment buildings, residential properties, commercial spaces, traffic conditions and building access. Customers may also need assistance with packing, furniture handling or transporting larger and more delicate belongings.

    Asher Movers provides local moving support intended to help customers coordinate these elements through a single moving service provider. The company’s approach includes customized moving solutions based on the size, location and requirements of each move.

    Company Response

    Asher Movers Local & Long Distance provides local and long-distance relocation services throughout Chicago and nearby suburbs. Its local moving services are designed to support customers who are relocating within the region while maintaining options for customers whose moves extend beyond the Chicago area.

    Additional details are available at: https://share.google/ARk5r1Acgk9hptlQg

    The company states that its movers are licensed and insured and serve homeowners, businesses, students and military families.

    Local Moving Services

    Asher Movers’ service offerings include:

    • Local moving
    • Long-distance moving
    • Commercial relocation
    • Apartment moving
    • Packing services
    • Piano moving
    • Specialty moving solutions

    The company’s local moving services can be used for a range of residential and commercial relocation needs. Packing and specialty moving options are also available for customers who require additional assistance with preparing and transporting their belongings.

    Company Background

    Asher Movers is a Chicago-area moving company serving customers throughout Chicago and nearby suburbs. The company provides local and long-distance moving, commercial relocation, apartment moving, packing, piano moving and specialty moving services.

    Its services are intended for homeowners, businesses, students, military families and other customers planning residential or commercial relocations.

    Executive Statement

    Asher Movers said: “Every move has different requirements, which is why we focus on understanding the details of each relocation and providing services that fit the customer’s needs. Our local moving services give Skokie-area customers an option for professional assistance when planning a move within the Chicago region.”

    Future Outlook

    Asher Movers plans to continue supporting residential and commercial customers throughout the Chicago area with local and long-distance relocation services. The company’s expanded local moving offering is intended to provide customers in Skokie and surrounding communities with access to coordinated moving and packing solutions for upcoming relocations.

    About Asher Movers Local & Long Distance

    Asher Movers Local & Long Distance is a Chicago-area moving company providing local moving, long-distance moving, commercial relocation, apartment moving, packing, piano moving and specialty moving services. The company serves Chicago and nearby suburbs and provides relocation solutions for homeowners, businesses, students and military families.

    Media Contact

    Asher Movers Local & Long Distance
    Email: info@ashermovers.com
    Phone: 773-638-4167
    Website: ashermovers.com

  • How to Build Integration Flows in SAP Cloud Platform Integration

    How to Build Integration Flows in SAP Cloud Platform Integration

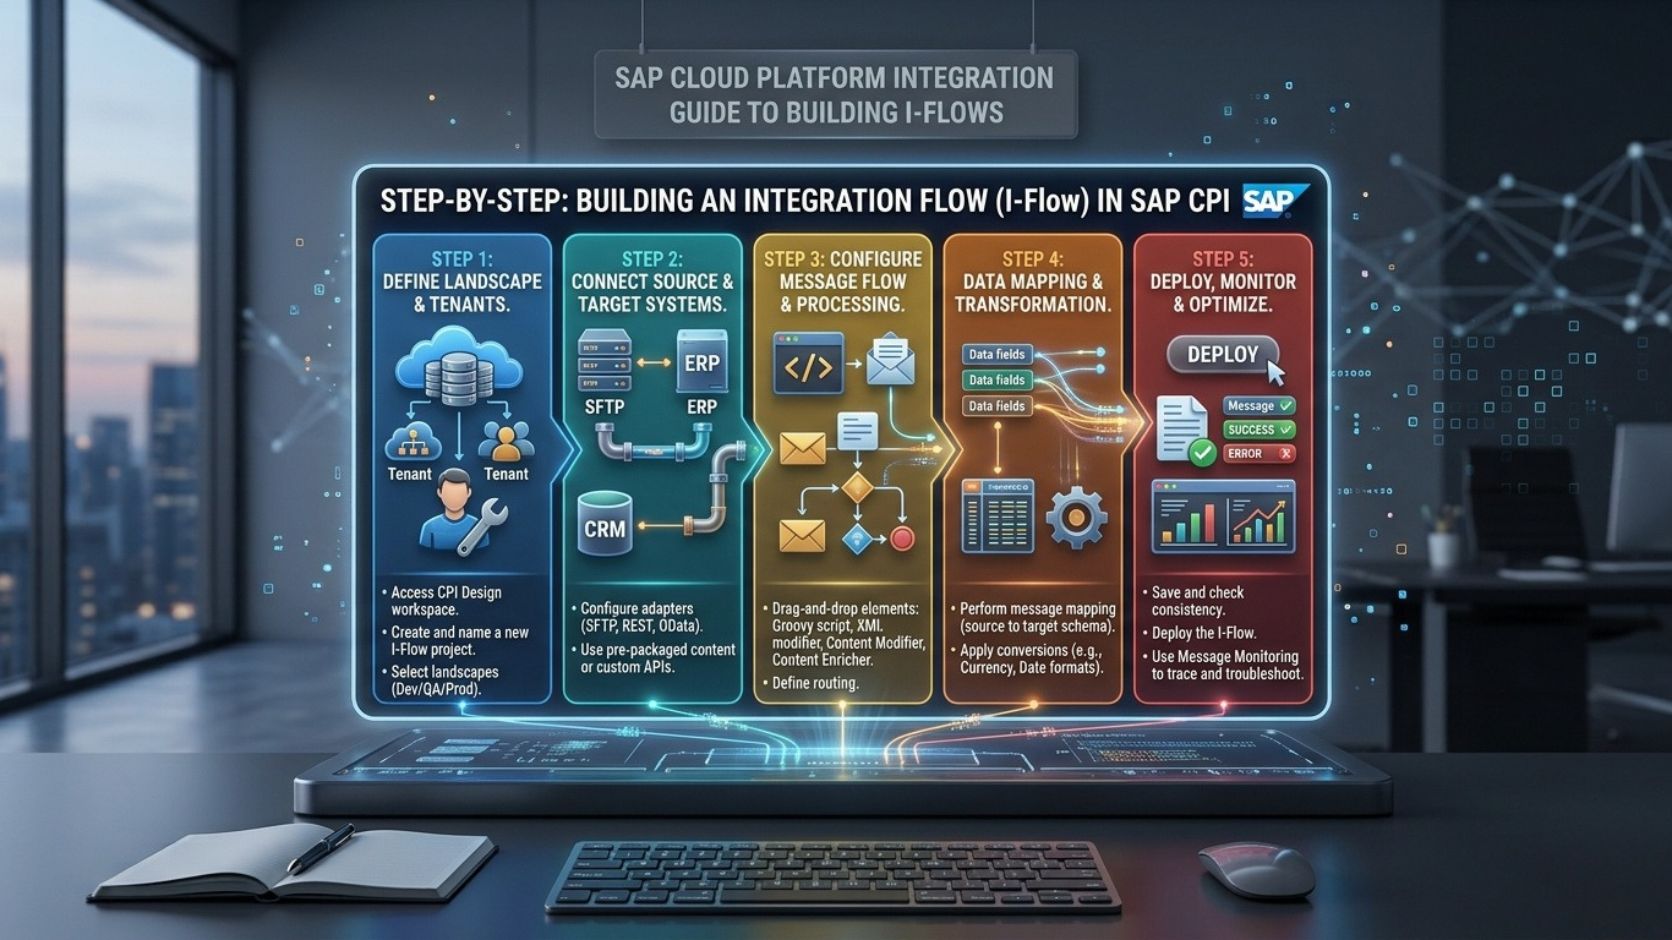
    SAP Cloud Platform Integration provides a cloud-based environment for connecting SAP applications, non-SAP systems, APIs, databases, and external business platforms. Integration flows are the main building blocks used to define how information moves between these systems.

    SAP Cloud Platform Integration is commonly called SAP CPI. The capability is now part of SAP Integration Suite and is generally referred to as Cloud Integration. An integration flow can receive a message, transform its data, apply business logic, route the message, and deliver it to a target system.

    For beginners, understanding how to build an integration flow requires knowledge of sender and receiver systems, adapters, message mapping, content modification, routing, security, deployment, testing, and monitoring. Destinations can also be relevant when applications need centrally configured connection information.

    What Is an Integration Flow?

    An integration flow, commonly called an iFlow, defines how a message travels between systems.

    A basic integration flow contains a sender, processing logic, and receiver.

    Sender System → Integration Flow → Receiver System

    For example, an e-commerce application can send an order to SAP Cloud Platform Integration. The integration flow can receive the order through an HTTP interface, validate the data, transform the message, and send the processed order to SAP S/4HANA.

    An integration flow can contain several processing steps. The exact design depends on the business process and technical requirements.

    How SAP Cloud Platform Integration Works

    SAP Cloud Platform Integration processes messages through a runtime environment.

    The sender system starts the communication. A sender adapter receives the message. The integration flow then processes the message using configured components.

    Processing may include data transformation, message mapping, filtering, routing, validation, or scripting.

    The receiver adapter then sends the processed message to the target system.

    A typical flow can look like:

    Source → Sender Adapter → Mapping → Router → Receiver Adapter → Target

    This structure allows different systems to communicate even when they use different data formats or protocols.

    What You Need Before Building an Integration Flow

    Before creating an integration flow, the source and target systems should be clearly identified.

    You should know the communication protocol supported by each system. This may be HTTP, REST, SOAP, SFTP, OData, IDoc, or another supported technology.

    The source and target data structures should also be available. This is important when message mapping is required.

    Authentication information must also be configured securely.

    For API-based integrations, the endpoint, HTTP method, request structure, response structure, and authentication method should be known before development begins.

    A clear technical design reduces errors during implementation.

    Step 1: Define the Integration Requirement

    The first step is to define what information needs to move between the systems.

    For example, consider a customer synchronization scenario between SAP S/4HANA and a CRM application.

    The requirement may be:

    SAP S/4HANA → Customer Data → CRM Platform

    The design should identify which fields are required.

    For example:

    Customer ID

    Customer Name

    Email Address

    Phone Number

    Country

    The integration should also define whether the process is synchronous, asynchronous, scheduled, or event-driven.

    The expected message volume and frequency should also be considered.

    Step 2: Identify the Sender and Receiver

    The sender is the system that provides the initial message.

    The receiver is the system that receives the processed information.

    For example, SAP S/4HANA can be the sender while Salesforce is the receiver.

    In another scenario, Salesforce can send information to SAP S/4HANA.

    The direction of communication determines the sender and receiver configuration.

    Some integration scenarios can also contain multiple receivers. A router can direct different messages to different target systems.

    Step 3: Create the Integration Flow

    After defining the requirement, the integration flow can be created in the SAP integration environment.

    The developer defines the integration process and adds the required components.

    The initial flow normally contains a sender and receiver connection.

    The graphical development environment allows processing components to be placed between them.

    The flow can then be configured according to the business process.

    Step 4: Configure the Sender Adapter

    The sender adapter determines how the integration flow receives information.

    The appropriate adapter depends on the source system.

    For example, an HTTP adapter can receive requests from an HTTP-based application or REST API.

    A SOAP adapter can receive SOAP messages.

    An SFTP-based scenario can receive files from an SFTP server.

    An IDoc-based integration can use the appropriate SAP connectivity mechanism.

    The adapter configuration normally includes endpoint and authentication-related settings.

    Step 5: Configure the Receiver Adapter

    The receiver adapter determines how the integration flow sends information to the target system.

    For example, an HTTP receiver adapter can call an external REST API.

    A SOAP receiver adapter can communicate with a SOAP service.

    An SFTP receiver can transfer a file to an SFTP server.

    The receiver configuration depends on the protocol, endpoint, authentication method, and target system requirements.

    Step 6: Configure Destinations

    Destinations can be used in SAP cloud environments to provide connection information for applications and services.

    A Destination can contain information such as the target URL, authentication configuration, and other connection properties.

    For example, an application may need to communicate with an external API. Instead of storing the endpoint and authentication configuration directly inside application logic, a configured Destination can provide the required connection information.

    Destinations are particularly relevant when the same application needs different connection settings for development, testing, and production.

    For example:

    Development → Test Endpoint

    Production → Live Endpoint

    Using Destinations can help separate environment-specific connection configuration from application logic.

    The exact Destination configuration depends on the target service and authentication method.

    Step 7: Add Message Mapping

    Message mapping is required when the source and target systems use different data structures.

    For example, the source system may send:

    customer_id

    customer_name

    email

    The target system may require:

    CustomerNumber

    FullName

    EmailAddress

    A mapping connects the source fields to the required target fields.

    Mapping can also transform values, combine fields, apply conditions, and convert data types.

    For example, FirstName and LastName can be combined into a FullName field.

    Message mapping should match the target system’s interface requirements.

    Step 8: Add Content Modifiers

    Content modifiers can change message headers, properties, and message bodies.

    They can be used when additional information needs to be added to the message during processing.

    For example, a property can store an order number or another value that is needed later in the integration flow.

    Content modifiers can also prepare a message before it reaches another processing step.

    The configuration depends on the information required by the integration scenario.

    Step 9: Add Routing Logic

    A router allows the integration flow to make decisions based on message content or other conditions.

    For example, an order integration can use the country field to determine the target system.

    An order from Germany can follow one processing path, while an order from the United States can follow another.

    The structure can be represented as:

    Incoming Message → Router → Condition A / Condition B → Different Processing Paths

    Routing is useful when a single integration flow needs to support multiple business scenarios.

    Step 10: Transform the Message

    The source and target systems may use different data formats.

    For example, the source may provide XML while the target API requires JSON.

    The integration flow can transform the message into the format expected by the receiver.

    Transformation can include changing field names, converting data types, restructuring content, and modifying values.

    The transformation method should match the target system’s interface specification.

    Step 11: Add Validation

    Validation helps ensure that required information is available before the message reaches the target system.

    For example, an order may require:

    Order ID

    Customer ID

    Product ID

    Quantity

    If a required field is missing, the message can be routed to an error-handling process instead of being sent to the target system.

    Validation can reduce unnecessary requests to target systems and make integration errors easier to identify.

    Step 12: Configure Authentication and Security

    Security configuration depends on the source and target systems.

    Common authentication methods include OAuth, basic authentication, client certificates, and other supported methods.

    HTTPS can protect data during transmission.

    Authentication information should be stored using secure configuration mechanisms.

    Sensitive credentials should not be unnecessarily exposed in scripts, message bodies, or integration logs.

    Security requirements should be defined before the integration flow is deployed.

    Step 13: Add Error Handling

    Integration flows should account for technical and business errors.

    A technical error can occur when a target system is unavailable. Authentication can also fail because credentials are incorrect or expired.

    A business error can occur when required data is missing or invalid.

    SAP Cloud Platform Integration provides exception-handling capabilities that can be incorporated into integration flows.

    An exception subprocess can capture an error and execute a separate processing path.

    For example:

    Processing Error → Exception Subprocess → Error Handling

    The error-handling process can log the problem or send information to another system, depending on the integration requirements.

    Step 14: Test the Integration Flow

    Testing should be performed before production deployment.

    The test should use realistic message structures and values.

    For example, an order integration should test valid orders and invalid orders.

    The test should verify whether the sender can communicate with the integration endpoint, whether mapping works correctly, and whether the receiver accepts the final message.

    Authentication and error conditions should also be tested.

    Testing can identify configuration problems before the integration is used for live business transactions.

    Step 15: Deploy the Integration Flow

    After testing, the integration flow can be deployed to the runtime environment.

    Deployment makes the integration artifact available for message processing.

    The developer or administrator should confirm that the required connection configuration, authentication, endpoints, and other dependencies are available.

    If Destinations are used, the appropriate Destination configuration should also be available in the relevant environment.

    Development, testing, and production environments can have different endpoint and authentication configurations.

    Step 16: Monitor Message Processing

    After deployment, message processing should be monitored.

    Monitoring can show whether messages are successful or failed.

    If a message fails, the processing information can help identify the problem.

    Common causes include:

    • Invalid credentials
    • Incorrect endpoint
    • Mapping errors
    • Missing fields
    • Target-system errors
    • Network problems

    Monitoring information can be used to troubleshoot the integration and improve reliability.

    Example: Building an S/4HANA to CRM Integration

    Consider an integration where SAP S/4HANA sends customer information to a CRM platform.

    The architecture can be:

    SAP S/4HANA → Integration Flow → CRM Platform

    The sender adapter receives the customer information.

    The integration flow validates required fields such as customer ID and email address.

    Message mapping then converts the S/4HANA structure into the CRM structure.

    A content modifier can add required metadata.

    The receiver adapter sends the transformed message to the CRM API.

    If the CRM API rejects the request, the exception-handling process can capture the failure.

    The message can then be reviewed through monitoring.

    Example: API-Based Integration Flow

    An API integration can use the following structure:

    External Application → HTTP Endpoint → Cloud Integration → Mapping → Target API

    The external application sends a request.

    The sender endpoint receives the request.

    The integration flow validates and transforms the data.

    The receiver adapter calls the target API.

    The response can then be processed and returned to the calling application when the integration pattern requires a response.

    This approach is common when cloud applications need to exchange data through REST APIs.

    Common Mistakes When Building Integration Flows

    Integration flow problems can occur when technical requirements are not defined clearly.

    Using the wrong adapter can prevent communication. Incorrect field mappings can produce invalid data. Missing authentication configuration can cause authorization failures.

    Another common problem is insufficient error handling. Without proper exception processing, identifying the cause of failed messages can take longer.

    Incorrect endpoint configuration can also cause connection failures.

    Connection information should be checked carefully, particularly when different development, testing, and production environments are used.

    Destinations should also be configured consistently when they are part of the integration architecture.

    Best Practices for Building Integration Flows

    Integration flows should have clear names and organized processing steps.

    Only required processing components should be included. Unnecessary transformations can increase complexity.

    Authentication information should be handled securely.

    Error handling should be designed before production deployment.

    Message mappings should match the current source and target interface specifications.

    Testing should include both successful and failed scenarios.

    Monitoring should be used after deployment to identify message-processing problems.

    Environment-specific connection settings should be separated from core integration logic where the architecture supports this approach.

    Frequently Asked Questions

    What is an integration flow in SAP Cloud Platform Integration?

    An integration flow is a graphical representation of the processing logic used to move messages from a sender system to a receiver system. It can contain adapters, mappings, routers, transformations, and error-handling components.

    How do I start building an integration flow?

    Start by identifying the source and target systems, communication protocols, message structures, authentication requirements, and business rules. Then create the integration flow and configure the required sender, processing, and receiver components.

    What are Destinations used for?

    Destinations provide connection information that applications and services can use to communicate with target systems. They can contain endpoint and authentication configuration.

    Can Destinations be used for different environments?

    Yes. Destinations can provide environment-specific connection information. Development, testing, and production environments can use different target endpoints and authentication configurations.

    Which adapters can be used in an integration flow?

    The available adapter depends on the integration scenario. Common technologies include HTTP, SOAP, SFTP, OData, IDoc, and ProcessDirect.

    What is message mapping?

    Message mapping converts source data into the structure required by the target system. It can connect fields, change values, combine data, and convert data types.

    How do I test an integration flow?

    Testing should verify connectivity, authentication, message structure, mapping, routing, target-system communication, and error handling. Both successful and failed scenarios should be tested.

    How are integration flow errors handled?

    Errors can be processed through exception-handling mechanisms. Failed messages can be investigated using message-processing and monitoring information.

    Is SAP Cloud Platform Integration still used?

    The technology has evolved into the Cloud Integration capability within SAP Integration Suite. SAP CPI remains a widely used term for the technology.

    Conclusion

    Building integration flows in SAP Cloud Platform Integration involves several connected stages. The process starts with identifying the source and target systems and selecting the appropriate communication technologies.

    The integration flow then connects these systems through adapters and processing components. Message mapping and transformation ensure that the target system receives the required data structure. Routing and validation can apply business rules, while security protects communication and access.

    Destinations can provide structured connection information for applications and services. They can also help separate environment-specific connection settings from application logic.

    After development, the integration flow should be tested, deployed, and monitored. Error handling should also be included so that technical and business failures can be identified and managed.

    With these components working together, SAP Cloud Platform Integration can support integration between SAP S/4HANA, SAP SuccessFactors, APIs, cloud applications, and third-party systems within a structured enterprise integration architecture.

  • Same-Day Stump Grinding Now Available in Cincinnati

    Same-Day Stump Grinding Now Available in Cincinnati

    Valentine Services – Stump Grinding has announced the availability of same-day stump grinding services for residential and commercial customers in Cincinnati and surrounding communities, providing property owners with an option for addressing unwanted tree stumps, exposed surface roots and related tripping hazards without an extended scheduling process.

    The new service expands the company’s existing stump grinding and removal capabilities across Cincinnati, Ohio, and Northern Kentucky. Valentine Services – Stump Grinding serves homeowners, businesses, property managers and contractors seeking to clear stumps and improve the usability and appearance of outdoor spaces.

    Addressing Common Stump and Root Hazards

    Tree stumps can remain after tree removal and may interfere with landscaping, construction projects, lawn maintenance and routine property use. Surface roots can also create uneven areas that present potential tripping concerns or complicate future landscaping work.

    Additional details are available at: https://share.google/FhICefWA6JHjY7oiz

    For customers who need stump-related work completed promptly, same-day availability is designed to provide a more immediate service option when scheduling and site conditions allow.

    Company Response

    Valentine Services – Stump Grinding provides stump grinding and related property-clearing services throughout Cincinnati and Northern Kentucky. The company works with customers on projects ranging from individual residential stumps to larger commercial and contractor-related jobs.

    “Same-day service gives property owners another option when a stump is getting in the way of a project or creating an unwanted obstacle on the property,” a Valentine Services representative said. “Our focus is on completing the work efficiently while maintaining clear communication with customers throughout the process.”

    Service Details

    Valentine Services – Stump Grinding offers services that include:

    • Same-day stump grinding, subject to scheduling and site conditions
    • Residential stump grinding
    • Commercial stump grinding
    • Root grinding
    • Large stump removal
    • Wood chip cleanup
    • Site restoration
    • Stump removal for contractors and property managers

    The company provides free estimates and serves communities throughout the Cincinnati area and Northern Kentucky.

    Service Area

    Valentine Services – Stump Grinding serves Cincinnati and nearby communities, including Blue Ash, Mason, West Chester, Fairfield, Loveland and Hamilton in Ohio, as well as Florence, Covington, Erlanger, Burlington and Hebron in Northern Kentucky.

    Company Background

    Valentine Services – Stump Grinding provides professional stump grinding and stump removal services for residential, commercial and contractor customers. The company specializes in removing unwanted stumps, surface roots and potential tripping hazards while helping customers prepare properties for landscaping, construction and general outdoor use.

    The company is licensed and insured and emphasizes responsive service, customer communication and site cleanup. Additional information about Valentine Services – Stump Grinding is available through its business website, 513stumps.com.

    Future Outlook

    The introduction of same-day stump grinding expands scheduling options for Cincinnati-area property owners who need stump-related work addressed on a shorter timeline. Valentine Services – Stump Grinding plans to continue serving residential and commercial properties throughout Greater Cincinnati and Northern Kentucky as demand for stump removal and property maintenance services continues.

    About Valentine Services – Stump Grinding

    Valentine Services – Stump Grinding provides stump grinding and stump removal services throughout Cincinnati, Ohio, Northern Kentucky and nearby communities. The company serves homeowners, businesses, property managers and contractors with residential and commercial stump grinding, root grinding, large stump removal, chip cleanup and site restoration. Valentine Services – Stump Grinding is licensed and insured and offers free estimates.

    Media Contact

    Valentine Services – Stump Grinding
    Email: bikemanjrv95@gmail.com
    Phone: 513-570-4626
    Website: 513stumps.com

  • Professional Shoulder Pain Care Now Available in Sydney

    Professional Shoulder Pain Care Now Available in Sydney

    Spine and Posture Care Chiropractor Sydney has announced the availability of professional chiropractic care for people experiencing shoulder pain in Sydney, adding another area of musculoskeletal care to the clinic’s existing focus on spinal health, posture and related pain conditions.

    Shoulder pain can affect movement, work, exercise and everyday activities. Identifying factors that may contribute to discomfort is an important part of developing an appropriate care plan, particularly when symptoms occur alongside neck, upper-back or postural concerns.

    Market Challenge

    Shoulder discomfort can have a range of contributing factors, and determining the source of a patient’s symptoms may require an assessment of more than the shoulder itself. Posture, spinal movement, muscle function and other musculoskeletal factors can be relevant when considering a person’s overall presentation.

    For Sydney residents seeking care, access to an individualized approach can be particularly relevant when shoulder symptoms occur alongside recurring neck or upper-back discomfort.

    Company Response

    Spine and Posture Care has expanded its chiropractic services to include care for patients presenting with shoulder pain. The clinic’s chiropractors assess each patient individually and develop treatment programs based on their reported symptoms, physical presentation and treatment needs.

    The clinic combines spinal therapy, muscle work and rehabilitation within its broader approach to chiropractic care. Patients receive one-on-one appointments and explanations of their condition and recommended treatment approach.

    The new shoulder pain service complements the clinic’s existing work with lower-back, mid-back and neck pain, sciatica, slipped discs, headaches and posture-related concerns.

    Shoulder Pain Care in Sydney

    The clinic’s approach is centered on identifying potential contributing factors rather than treating shoulder symptoms in isolation. Depending on the individual assessment, care may incorporate:

    • Chiropractic and spinal therapy
    • Muscle-focused treatment
    • Rehabilitation exercises
    • Postural assessment and related care
    • Individualized treatment planning
    • Education about the factors relevant to a patient’s symptoms

    Treatment recommendations are determined on an individual basis following assessment.

    One-on-One Chiropractic Care

    Spine and Posture Care provides one-on-one care from experienced chiropractors at its Sydney City clinic, located between Wynyard, Martin Place and Circular Quay.

    The clinic works with patients experiencing a range of pain and posture-related concerns and emphasizes clear communication throughout the treatment process. Its programs are designed around each patient’s circumstances rather than applying a single approach to every presentation.

    The clinic reports having received hundreds of five-star reviews from patients.

    Executive Quote

    “Shoulder pain can present alongside issues involving the neck, upper back, posture or surrounding muscles, so understanding the individual presentation is an important first step,” said a representative of Spine and Posture Care. “Our approach is to assess each patient and explain the factors we identify before developing a treatment plan that is appropriate to their needs.”

    Future Outlook

    The addition of shoulder pain care reflects Spine and Posture Care’s broader focus on musculoskeletal health and individualized chiropractic treatment in Sydney. The clinic will continue providing services addressing spinal pain, posture and related conditions while supporting patients through treatment and rehabilitation programs.

    Additional details are available at: https://share.google/O8QKN1qUIOwGNrFeU

    People experiencing persistent, severe or unexplained shoulder pain should seek an appropriate health assessment to determine the cause and the most suitable course of care.

    About Spine and Posture Care Chiropractor Sydney

    Spine and Posture Care is a chiropractic clinic in Sydney City, NSW. The clinic focuses on identifying factors associated with pain and posture-related concerns and provides individualized chiropractic treatment programs.

    Its chiropractors work with conditions including lower-back, mid-back and neck pain, sciatica, slipped discs, headaches, poor posture and shoulder pain. Treatment programs may combine spinal therapy, muscle work and rehabilitation, with an emphasis on one-on-one care and clear explanations.

    The clinic is conveniently located between Wynyard, Martin Place and Circular Quay.

    Media Contact

    Spine and Posture Care Chiropractor Sydney
    Email: Info@spineandposturecare.com.au
    Phone: +61 2 8040 9922
    Website: https://spineandposturecare.com.au/

  • How Open Banking and Card Issuing APIs Are Converging

    How Open Banking and Card Issuing APIs Are Converging

    Open banking APIs and card issuing APIs once served separate roles. That boundary is fading. Shared access to account data, payment initiation, and card controls is creating a more unified financial stack. This shift helps firms verify funds faster, manage risk with better context, and build smoother payment flows. As infrastructure and regulation evolve together, the practical impact of this convergence becomes harder to ignore.

    How Open Banking and Card APIs Differ

    At a basic level, open banking APIs and card issuing APIs serve different functions within financial infrastructure. Open banking APIs enable secure access to account data and payment initiation across institutions, supporting transaction transparency, data privacy, and stronger consumer trust. Their value often depends on API security standards, consent management, and clearer financial literacy for users reviewing shared data.

    Card issuing APIs, by contrast, let businesses create, manage, and control payment cards for spending. They focus on authorization rules, card lifecycle management, and embedded payment flows that shape user experience at the point of purchase.

    While both can influence market competition and innovation acceleration, card issuing APIs are primarily operational tools for disbursements, expenses, and branded payments, rather than mechanisms for broad account connectivity or standardized financial data access.

    Why Banking and Card Issuing Are Converging

    The convergence of banking and card issuing is being driven in part by shared infrastructure, as providers increasingly rely on common API frameworks, compliance controls, and payment rails.

    It is also being accelerated by real-time data synergies that improve authorization, fraud monitoring, and account-based decisioning.

    Together, these shifts are supporting a more unified embedded finance model in which banking and card functionality are delivered through integrated platforms.

    Shared Infrastructure Drivers

    As digital finance platforms have matured, open banking and card issuing have increasingly relied on the same underlying infrastructure: APIs, cloud-native processing, identity verification, fraud controls, and real-time ledgering.

    This shared infrastructure reduces duplication across product lines and enables providers to build once, then extend capabilities across payments, account access, onboarding, and compliance workflows.

    API standardization has further accelerated convergence by making integration patterns more predictable for fintechs, banks, processors, and enterprise platforms.

    Common authentication methods, modular service layers, and reusable orchestration tools support faster deployment while lowering operational complexity.

    The same vendors often now supply tokenization, KYC, transaction monitoring, dispute management, and ledger services to both banking and issuing programs.

    As a result, institutional boundaries matter less than technical architecture, platform design, and the economics of scalable financial software.

    Real-Time Data Synergies

    Shared infrastructure has made convergence technically feasible, but real-time data flows are making it commercially and operationally compelling. As banking and card issuing APIs interact more closely, data interoperability enables faster decisions across payments, account activity, and funding events.

    Providers can combine transaction analytics with customer insights to refine authorization logic, detect anomalies, and strengthen risk management without adding operational friction.

    These synergies also improve user experience by supporting timely notifications, balance-aware spending controls, and more accurate cash-flow visibility. Real-time signals can expand financial inclusion by helping providers assess behavior beyond traditional credit metrics and respond to changing circumstances quickly.

    At the market level, continuous data exchange creates innovation opportunities, allowing firms to test responsive products and deepen ecosystem collaboration among banks, issuers, fintechs, and processing partners globally.

    Unified Embedded Finance

    Convergence in embedded finance is being driven by demand for unified products that combine account functionality, payment issuance, and programmable controls within a single user experience.

    This shift reflects a broader market preference for fewer integrations, faster deployment, and more consistent financial workflows across digital platforms.

    What’s Driving This Convergence?

    Several market forces are accelerating the convergence of open banking and card issuing APIs. Institutions are pursuing stronger customer experience through faster onboarding, smoother payments, and more responsive financial services.

    Technology evolution and digital transformation have lowered integration barriers, while market competition is pushing providers to differentiate with flexible, data-driven offerings. Regulatory changes in many regions are also encouraging standardized access, transparency, and portability across financial ecosystems.

    At the same time, consumer demand for convenience, personalization, and real-time control continues to rise. Providers are responding through innovation trends that support broader financial inclusivity and more tailored products.

    Stronger security measures remain essential as data sharing expands, prompting investment in authentication, monitoring, and compliance. Industry partnerships further accelerate progress by combining infrastructure, distribution, and specialized capabilities across banks, fintechs, and platforms.

    Bridging Local Users and Global Commerce

    In many markets, the gap between local payment habits and global online commerce remains wide: international checkout pages expect card credentials that local banking products don’t always provide. API-issued virtual cards bridge that gap at software speed. Nigeria is one of the clearest examples of this dynamic, and the growth of the virtual card API in Nigeria ecosystem shows how quickly access expands when issuance becomes an integration rather than a banking relationship.

    How Open Banking and Card APIs Work Together

    Open Banking and card issuing APIs operate together by linking bank account data with card-based payment capabilities.

    This enables real-time account verification, which supports faster onboarding, stronger fraud controls, and more accurate transaction approval.

    It also supports unified payment flows by connecting funding, authorization, and settlement processes across account-to-account and card transactions.

    Real-Time Account Verification

    Linking bank-account data with card issuing workflows enables real-time account verification at the moment of onboarding or funding. By combining open banking access with issuer controls, platforms can confirm account ownership, status, and recent activity before enabling a card or approving an initial load. This reduces manual review, accelerates activation, and improves decision accuracy.

    Open banking APIs supply authenticated account details, while card issuing systems apply those signals to compliance, fraud screening, and operational rules. The result is real-time verification supported by current financial data rather than static user inputs alone.

    Account synchronization further helps keep records aligned when account credentials, balances, or permissions change. In practice, this convergence supports faster onboarding, fewer failed funding attempts, and stronger confidence that linked accounts are valid, active, and authorized.

    Unified Payment Flows

    Unify payment orchestration by combining open banking connectivity with card issuing APIs into a single flow for funding, disbursement, and transaction control.

    This model creates unified interfaces that support streamlined transactions across bank transfers, virtual cards, and physical cards. It improves customer experience by reducing handoffs between systems while enabling enhanced security through tokenization, authentication, and real-time account validation.

    Converged payment stacks also advance payment innovation by linking account data, card controls, and settlement logic within one operational framework.

    The result is stronger cost efficiency, faster technology integration, and better data analytics for risk monitoring and product design.

    How Real-Time Data Improves Card Issuing

    Real-time data strengthens card issuing by giving providers immediate visibility into account balances, transaction activity, and customer behavior. This access supports data driven insights that refine authorization decisions, improve enhanced security controls, and reduce unnecessary declines.

    Issuers can adjust dynamic limits in response to changing risk profiles or spending patterns, creating more accurate controls without delaying use.

    Real time personalization also improves the user experience by aligning card settings, alerts, and rewards with current activity. With predictive analytics, providers can anticipate anomalies, identify high value moments, and support instant approvals where risk appears acceptable.

    The result is more frictionless transactions, faster responses to customer needs, and a card program that operates with greater precision, adaptability, and reliability in competitive digital payment environments today.

    How Card Issuing Extends Open Banking

    Card issuing extends open banking by turning shared financial data into a usable payment instrument. Through API integration, institutions can connect account data, payment initiation, and issuance workflows within a unified framework.

    This convergence improves the cardholder experience by aligning spending tools with verified financial context and stronger user authentication.

    It also broadens the value of open banking beyond access and aggregation. Issuers can derive transaction insights that support personalized offerings, stronger customer engagement, and more adaptive controls.

    These capabilities enable innovative solutions while reinforcing security measures and regulatory compliance across onboarding, funding, and authorization processes.

    In parallel, card issuing can support financial inclusion by translating account visibility into practical, everyday payment access.

    Together, these layers make open banking more actionable, measurable, and commercially relevant for providers and end users alike.

    Top Use Cases for Open Banking and Cards

    These combined capabilities are most visible in the practical use cases they support across payments, lending, expense management, and digital commerce.

    • Instant account-to-card funding supports open banking innovation.
    • Real-time underwriting improves card issuing efficiency.
    • Smarter controls strengthen transaction security measures.
    • Personalized rewards drive user engagement strategies.
    • Seamless checkout advances digital wallet integration.

    Together, these applications enable customer experience enhancement through faster onboarding, verified identity, and clearer spending insights.

    They also widen financial inclusion impact by helping underserved users access tailored credit, prepaid products, and low-friction payment tools.

    For merchants and platforms, the model creates fintech collaboration opportunities around payouts, subscriptions, and embedded budgeting features.

    The result is a more responsive financial ecosystem that links data access with programmable card distribution and measurable commercial value across consumer and business journeys today.

    How Embedded Finance Teams Build With Both

    Embedded finance teams typically combine open banking connectivity with card issuing APIs by designing a unified product stack that links account data, payment initiation, identity checks, and programmable spending tools. This approach supports embedded finance models that prioritize API integration, consistent user experience, and stronger transaction efficiency across onboarding, funding, and payout flows.

    Teams usually align product, compliance, and operations functions around shared innovation strategies, using open banking for verification and account access while using cards for controlled disbursement and spend management.

    The result is cost reduction through fewer intermediaries, reinforced security measures through layered controls, and broader scalability options as volumes grow. By responding to market trends with modular architecture, firms can adapt faster, launch differentiated services, and build a measurable competitive advantage in increasingly connected financial ecosystems.

    What Developers Need From a Unified API

    Because integration complexity rises quickly across payment, account, and compliance workflows, developers need a unified API that presents open banking and card issuing functions through consistent authentication, standardized schemas, and predictable event handling.

    Strong developer experience depends on API standardization that reduces integration challenges and supports reusable components across products. Teams also expect scalability solutions, resilient security protocols, efficient user authentication, and documentation clarity that shortens onboarding and debugging cycles.

    • Consistent endpoints accelerate implementation
    • Clear webhooks improve system reliability
    • Testing frameworks reduce deployment risk
    • Version control limits breaking changes
    • Support resources speed issue resolution

    A capable platform aligns data models, sandbox behavior, and production performance. It enables faster iteration while preserving observability, reducing maintenance overhead, and helping engineering teams deliver connected financial features with greater confidence across markets.

    Compliance Risks in Converged Payments

    Converged payments introduce compliance complexity by placing open banking and card issuing activities under overlapping regulatory frameworks.

    This structure increases exposure to data sharing liabilities, particularly where consent management, data handling, and third-party access intersect.

    It can also create fraud monitoring gaps when controls are fragmented across systems, providers, or payment rails.

    Regulatory Overlap Challenges

    Three overlapping regulatory regimes often shape the risk profile of open banking and card issuing integrations: payments law, data protection rules, and card network requirements. Their convergence complicates regulatory compliance because firms must align legal frameworks, consumer protection duties, and industry standards across distinct operational models.

    Supervisory expectations may diverge by jurisdiction, while interoperability issues between banking APIs and card rails increase control complexity. Effective risk management therefore requires mapped obligations, coordinated governance, and auditable processes that support data privacy without slowing product delivery.

    Overlap can also create innovation barriers when approvals, technical certifications, and monitoring obligations duplicate effort.

    • Conflicting rules across products and markets
    • Divergent supervisory interpretations
    • Higher control and audit burdens
    • API and network interoperability issues
    • Slower launches from layered compliance demands

    Data Sharing Liabilities

    As overlapping rules increase governance complexity, liability exposure in data sharing becomes a central compliance concern for firms combining open banking connections with card issuing functions.

    Questions around data ownership, permitted use, retention, and onward transfer often remain contested across providers, processors, and banking partners. Clear consumer consent records are therefore essential to support lawful processing and dispute resolution.

    Where responsibilities are fragmented, liability shifts can occur after service failures, inaccurate disclosures, or unauthorized access to shared information.

    Effective risk management depends on harmonized compliance frameworks that define contractual duties, audit rights, breach notification timelines, and accountability standards.

    Strong data privacy controls and proportionate security measures help reduce exposure, but legal clarity remains critical when multiple entities collect, transmit, and monetize customer financial data across integrated payment ecosystems.

    Fraud Monitoring Gaps

    A persistent challenge in converged payments is the emergence of fraud monitoring gaps between open banking data flows and card issuing controls. Different rails often apply separate fraud detection rules, inconsistent risk scores, and uneven escalation paths. As a result, suspicious behavior may appear low risk in one system while triggering alerts in another, weakening transaction monitoring and delaying intervention.

    • Fragmented visibility across payment channels
    • Inconsistent customer authentication signals
    • Delayed alert sharing between providers
    • Conflicting case management procedures
    • Greater exposure to compliance breaches

    These gaps create operational blind spots for regulated firms. Institutions must align data standards, alert taxonomies, and response protocols across providers.

    Without coordinated oversight, reconciled records may satisfy reporting requirements while underlying fraud patterns remain undetected, increasing losses, investigation burdens, and scrutiny from regulators and banking partners.

    How Converged Payments Drive Fintech Growth

    Momentum in fintech often comes from converged payments, where open banking, card issuing, and embedded payment services operate through coordinated APIs rather than isolated systems.

    These converged channels strengthen payment ecosystems by reducing friction across account-to-account transfers, card rails, and digital wallets.

    As integration deepens, fintech innovation accelerates through faster launches, broader product design, and better user experience.

    Improved transaction speed supports retention, while stronger risk management across unified data flows helps sustain consumer trust.

    Convergence also sharpens market competition, allowing newer firms to challenge incumbents with lower costs and more adaptive services.

    In emerging and underserved segments, interoperable payment models can extend financial inclusion by connecting users, merchants, and platforms through flexible payment options.

    The result is scalable growth built on connectivity, efficiency, and more responsive financial infrastructure overall.

    Frequently Asked Questions

    How Long Does Integrating Both APIS Typically Take?

    It typically takes six weeks to six months to integrate both APIs, depending on complexity, compliance, and vendor readiness. The integration timeline varies with internal resource allocation, technical debt, testing requirements, and stakeholder coordination.

    Which Regions Have the Strongest Support for Converged Payment Infrastructure?

    Europe shows the strongest support, driven by European innovations; parts of Asia follow through Asian regulations, while North American trends remain robust but fragmented. Market challenges persist globally, including interoperability, licensing complexity, bank participation, and varied compliance standards.

    What Internal Teams Should Own Unified Banking and Card API Projects?

    Unified banking and card API projects should be owned by development teams with strong technical expertise, supported by clear project ownership, stakeholder involvement, collaboration strategies, and disciplined resource allocation across product, compliance, operations, and security functions.

    How Do Pricing Models Differ Between Open Banking and Card Issuing APIS?

    Open banking APIs typically use usage-based pricing strategies, subscription tiers, or freemium access, while card issuing APIs more often combine setup fees, per-card charges, interchange sharing, and compliance costs within broader revenue models structures.

    What Vendor Selection Criteria Matter Most for Long-Term Scalability?

    The theory that features alone ensure growth rarely holds; the decisive criteria are vendor reliability, scalability potential, integration flexibility, compliance standards, support services, and technology compatibility, which collectively determine whether long-term expansion remains operationally sustainable.

    Final words

    The convergence of open banking and card issuing APIs marks a significant shift in financial infrastructure. By combining real-time account data with flexible card controls, institutions can improve security, efficiency, and customer experience. This unified approach supports faster innovation, stronger compliance, and broader access to financial tools. As the saying goes, “necessity is the mother of invention.” In converged payments, that necessity is driving a more connected, responsive, and inclusive financial ecosystem for all stakeholders.